Step one
Prepare in the ledger
Close the period, then export a VAT summary from your ledger. This is the figure you are going to defend, so it should come from the same place your books came from.
Korea Compliance Guide
Korean compliance ties daily bookkeeping to VAT filings, electronic tax invoices, Hometax submissions, and statutory reporting. This guide explains each link and shows how to keep records consistent across the systems used in South Korea.
Chapter — VAT
VAT compliance depends on coding each sale and purchase with the correct VAT type when the invoice is recorded. Standard taxable, zero-rated, exempt, and non-deductible purchases each flow differently to the VAT report. Get that coding right in the ordinary working week and the filing becomes a review; get it wrong and the filing becomes a reconstruction.
The difficult part is not the report. The difficult part is that the four VAT types look almost identical on the invoice in front of you, and only one of them carries input VAT you can claim. When a purchase is coded wrong at entry, the error is invisible for weeks — every summary still balances — until the VAT report pulls the difference forward as a payable. By then the invoice, the date, and the person who coded it are three separate conversations.
Gensoft South Korea cloud accounting highlights VAT compliance and statutory reporting in its messaging, which is a signal about where the work actually concentrates. The practical rule is to treat the VAT code as part of the invoice data, not as a classification you add later.
Chapter — E-tax
An electronic tax invoice is the formal record for many B2B VAT transactions in Korea. The seller must issue it with the correct numbering and at the correct time; the buyer needs the matching record in hand to support input VAT. The two halves are one transaction, and they usually live in different systems.
Younglimwon K-System Evolve lists electronic tax invoice integration among its documented modules — a useful indicator of how ERP vendors treat issuance as core finance work rather than as a side office tool. When issuance sits in one place and ledger posting in another, the numbers drift apart quietly: an invoice issued but not posted, a posted line with no corresponding issuance, a supply date typed once as the invoice date and once as the delivery date.
The fix is procedural and it is boring. Keep issuance and ledger posting inside the same workflow, so that the moment an invoice is issued, the ledger already knows. Then a month-end count of issued invoices against posted lines is a check, not an investigation.
Seller side
Correct numbering, correct supply date, issued on time. Late or misdated issuance is the recurring problem, not the arithmetic.
Buyer side
Hold the matching record before you claim input VAT. A missing e-tax record surfaces as a small, annoying gap in the VAT report.
Chapter — Hometax
Step one
Close the period, then export a VAT summary from your ledger. This is the figure you are going to defend, so it should come from the same place your books came from.
Step two
Put the summary beside the Hometax view and walk the lines. Small gaps usually trace to a missing e-tax record or a miscoded exempt sale — both findable in minutes at this stage.
Step three
Only after the two views agree do you file. Retyping figures into the filing screen is where a clean ledger turns into a second, unreliable set of books.
Hometax is where many filings and invoice checks happen under the National Tax Service. HelloBooks emphasises VAT and National Tax Service workflows in its Korean positioning, reflecting how central that link is for businesses operating here. Even if you prepare figures in accounting software, reconcile totals to the Hometax drafts before submission.
Chapter — Statutory books
Beyond VAT, Korean businesses maintain statutory books and periodic reports that must tie to the general ledger. That ties back to three habits: locked periods, consistent account names, and retained attachments for major purchases. Without them, a query from an accountant or an auditor twelve months later becomes a search through files rather than a read of the record.
Douzone Bizon, positioned for established businesses and finance-heavy operations, is a useful example of why larger firms invest in stricter controls. The controls themselves are not complicated — smaller firms can adopt the same habit on a smaller scale: lock each month after review, and store the PDFs with the entry they belong to rather than in a folder that will drift.
Chapter — Errors
Most filing errors are repeats, not surprises. Three of them cause most of the pain.
The repeating three
The invoice is issued, the ledger posts, and the supply date ends up two days off. Frequently the invoice date is used instead of the actual date of supply. Fix: one place to enter the date, and it is not a spreadsheet cell you retype.
Entertainment and similar items are the usual suspects. The invoice is standard-rate, so the tax looks claimable, and it gets claimed by habit. Fix: a code on the account that blocks input VAT at the moment of entry, not at review.
Sales recorded in KRW without separating VAT, and a file that quietly stopped matching the ledger weeks ago. Fix: if a summary number cannot be traced back to a ledger line, it is not a summary — it is a guess.
First
Run an unreconciled-items report. Whatever it lists has not yet been decided.
Second
List the missing e-tax numbers beside the matching invoices.
Third
Have a second person review the VAT codes on the largest lines.
Thirty minutes on this routine saves days of correction later — mostly because it happens before the filing, when the numbers are still cheap to change.
Chapter — Software fit
A demo that works on your own recent invoices and bank lines tells you more about a system than any feature list. These are the questions worth asking in the room.
If a vendor answers these five with a feature list rather than a demonstration on your data, that is an answer too.
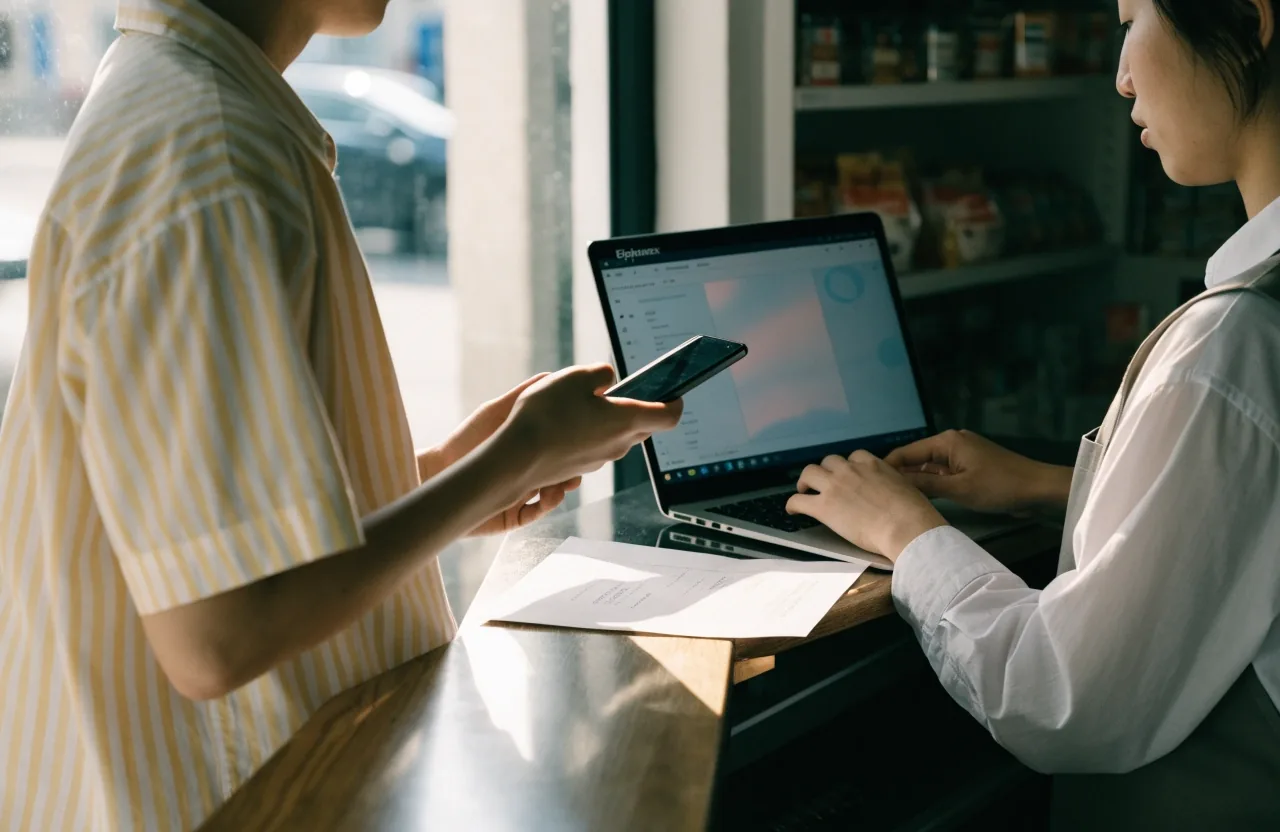
The chapters above describe records and systems, but the thing that decides whether a filing week is calm is where the record is created. If the e-tax invoice is issued at the counter while the customer is still standing there, the supply date, the amount, and the VAT treatment all get decided once — by the person who has the facts.
If the same invoice is rebuilt a week later from a pile of paper, everything about it becomes a memory exercise. Most of the value of cloud accounting in a Korean small business is not automation. It is that the record gets made in the moment, and the ledger never has to be reconstructed afterwards.
That habit scales. A shop with one counter and a firm with three branches run the same routine in principle: record where the work happens, review before the period locks, and reconcile to the forms before you submit them.
Questions
If your situation is more specific than these answers can hold, send the details and the team will look at it with you.
Coverage varies. Some handle general ledger and reporting well but need local add-ons or manual steps for VAT types and e-tax sync. Test with real Korean invoices before committing.
A direct link is helpful but not the only way. What matters is consistent VAT coding, matching e-tax records, and exports that reconcile to Hometax figures without retyping.
Next step
If your VAT coding, e-tax issuance and Hometax totals are already consistent, most of this guide is a confirmation. If one of the three is out of step, that is the one to fix first — before comparing software, and well before the next filing deadline.